ServicesVision Insurance
Vision Insurance in Oldsmar
We help you find a vision plan that pays for the eye exams, glasses and contacts you actually use. We check the network, the allowances and the fine print before you sign, so your first visit to the eye doctor holds no surprises.
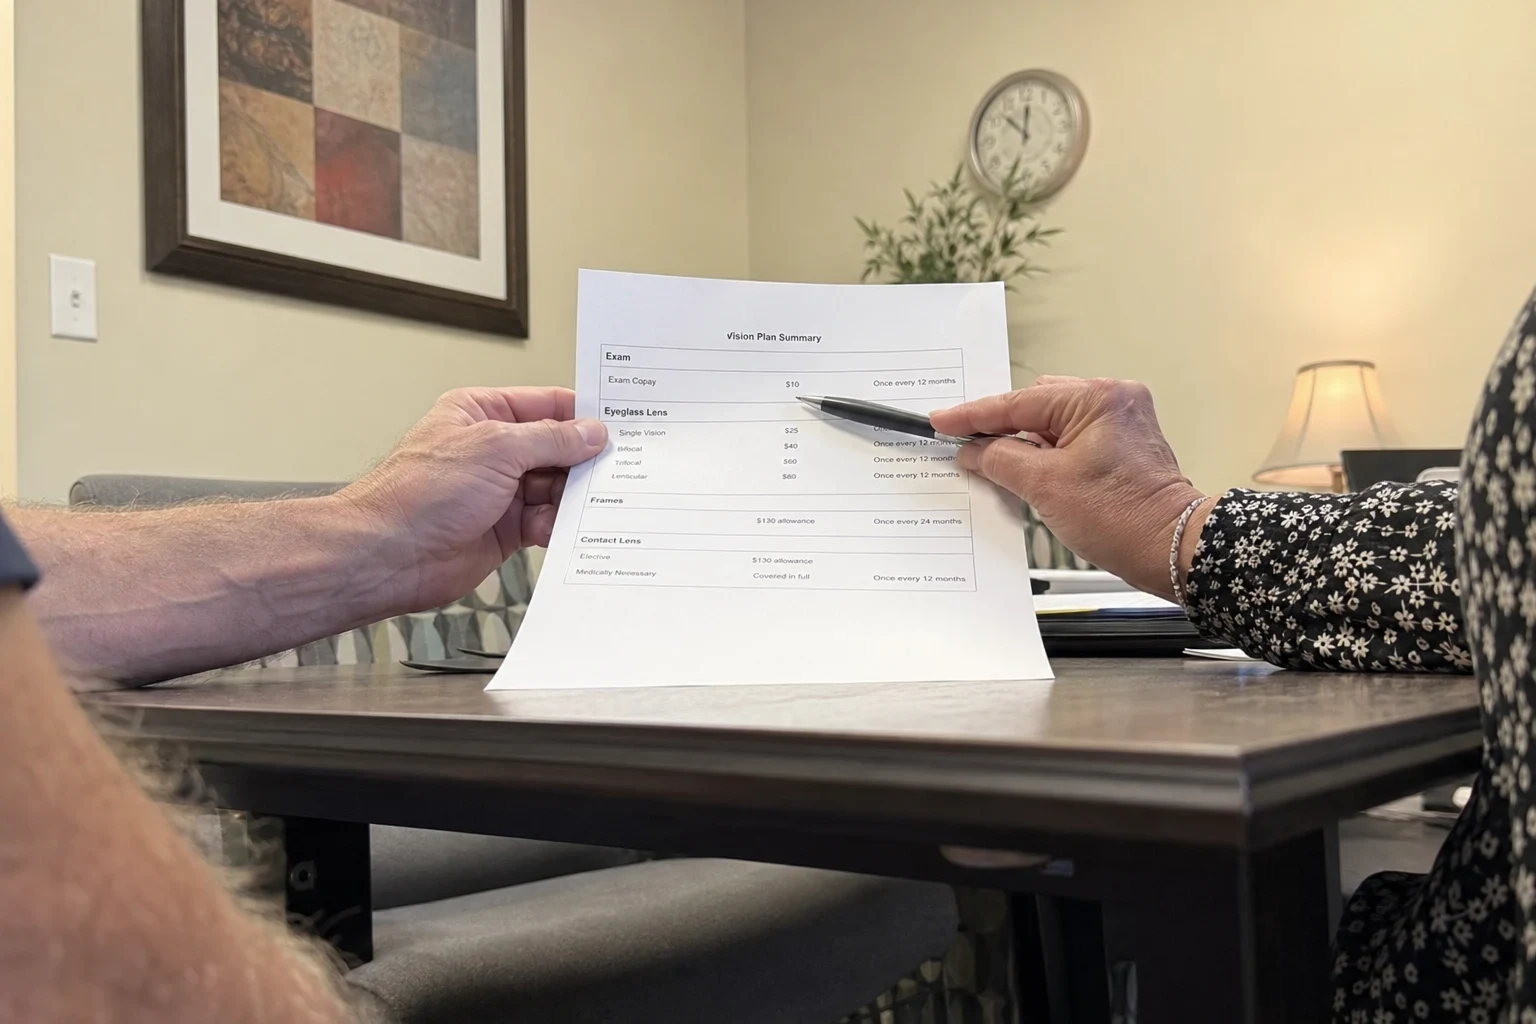
What a vision plan covers, and when it makes sense
Vision insurance is separate from your health coverage. It usually pays toward a routine eye exam, plus an allowance for frames and lenses or for contact lenses, on a set schedule such as once every 12 or 24 months. It generally does not cover medical eye problems like infections or injuries. Those go through your health plan.
A vision plan tends to pay off when someone in the family wears glasses or contacts, when kids need yearly checks, or when your job no longer offers vision benefits. If nobody needs corrective lenses, we will tell you that too. Paying for a plain exam yourself can cost less than a year of premiums.
We work carefully on purpose. The safe choice is the one with no hidden catches, so we look for the details that cause trouble later, like an eye doctor who is out of network or a frame allowance that only stretches to the cheapest rack, and we point them out before you enroll.
What we check when we review vision coverage
Your eye doctor's network status
Tell us who you see now, whether an independent optometrist or a retail optical shop, and we confirm they take the plan. Staying in network is usually the difference between a small copay and paying up front, then waiting on a reimbursement check.
Allowances and how often they reset
Plans differ on how much they put toward frames and contacts and how often you can use it. We set those numbers side by side so you can match them to how often you really replace your glasses.
Lens upgrades and extras
Progressive lenses, anti-glare coatings, blue-light filters and tinted sun lenses often cost extra. With bright sun most of the year here, many clients want sun lenses, so we check how each plan treats them.
Bundles versus stand-alone plans
Some carriers pair vision with a dental plan or add it to a health plan. We compare the bundle against a stand-alone vision plan, and our Dental Insurance page covers the other half of that choice.
Children's vision you may already have
Marketplace health plans include vision care for children under 19 as a required benefit. If your kids already have it through an ACA plan, we make sure you are not paying for the same coverage twice.
Signs it is time to look at vision coverage
- You replace glasses every year or two
- Frames and lenses add up fast, especially with coatings or progressives. A plan with a solid allowance can take a real bite out of that bill.
- Your kids are heading into school
- School screenings are quick checks, not full exams. Children who squint at the board or hold books close often need a proper exam, and a plan makes yearly visits easier to keep.
- You left a job that had vision benefits
- Employer vision coverage ends with the job. If you are now self-employed or between jobs, this is the moment to replace it before your next exam is due.
- You wear contact lenses
- Contacts are an ongoing cost. Many plans offer a separate contact lens allowance, and the right one can cover a good share of a year's supply.
- Your current plan keeps sending you out of network
- If your favorite eye doctor stopped taking your plan, you are paying more than you should. We can find a plan your doctor accepts.
How a vision plan review works
- 1
A short talk about how you use eye care
We ask who wears glasses or contacts, how often you get new ones, and which eye doctor you prefer. We can do this by phone, by video or at our office.
- 2
Side-by-side options from multiple carriers
We pull plans from several companies and line up the premium, exam copay, frame and contact allowances, and network. You see the trade-offs in plain terms.
- 3
An honest answer on whether it is worth it
We weigh a year of premiums against what you would likely spend out of pocket. If skipping the plan makes more sense, we say so and you leave with no pressure.
- 4
Enrollment and a final check
If you choose a plan, we walk you through enrollment and confirm the start date and member details. That way you know the coverage is active before you book your exam.
What affects the cost of vision coverage
Vision plan prices differ, and the lowest premium may not be the best deal once you factor in the allowances. The consultation is free, and having us look costs you nothing, since the company you pick pays us instead of you.
- People on the plan
- A plan for just you costs less than one with a spouse or kids. Family coverage tends to make sense when two or more people wear glasses.
- Allowance amount and reset schedule
- A bigger frame allowance, or one that renews every 12 months rather than every 24, generally raises the premium.
- How wide the network is
- Plans whose networks include major retail chains and independent doctors may be priced differently than plans with fewer choices.
- Extras for lenses and contacts
- When coatings, progressives or a larger contact lens allowance are built into the base benefit, you usually pay more each month and less at the store.
- Bundled versus on its own
- Pairing vision with dental or health coverage can shift the price. We price it both ways so you see the actual difference.
Vision insurance questions we hear often
- Does vision insurance cover eye problems like glaucoma or an eye injury?
- Usually not. Vision plans are built for routine exams and corrective eyewear. Medical eye care is generally billed to your health insurance, which is why we look at both together. Our Individual Health Insurance and Family Health Insurance pages explain how we help with that side.
- Can I use my vision plan to buy glasses online?
- Some plans reimburse part of an online purchase as out-of-network, and some do not. The reimbursement is often smaller than the in-network benefit. We check each plan's rules so you know before you order.
- Is there a waiting period before I can use it?
- Many vision plans have little or no waiting period, but the rules vary by carrier and by benefit. We read the plan details with you and tell you exactly when your exam and eyewear benefits begin.
- Do I have to wait for open enrollment?
- Often not. Stand-alone vision plans can usually be bought at any time of year. Children's vision that comes through an ACA Marketplace plan follows the open enrollment calendar, and our ACA Marketplace Plans page covers those dates.
- Do I need to come to your office?
- No. We meet by phone, by video or at our office, whichever is easier for you. Clients in Oldsmar and nearby towns like Palm Harbor and Westchase usually handle everything without leaving their desk.
- Will you push me into buying a plan?
- No. Our job is to show you clear options and an honest comparison. If a vision plan will not save you money, we will tell you, and you are free to walk away.
Find out if a vision plan is worth it for you
One call gets you a free consultation and side-by-side options from multiple carriers. If paying for exams and glasses yourself makes more sense, we will say so.